If you have been house hunting in Sacramento over the last few years, you know the drill. See it Saturday, offer Saturday night, waive everything, lose anyway.
That is not the market we are in this fall.
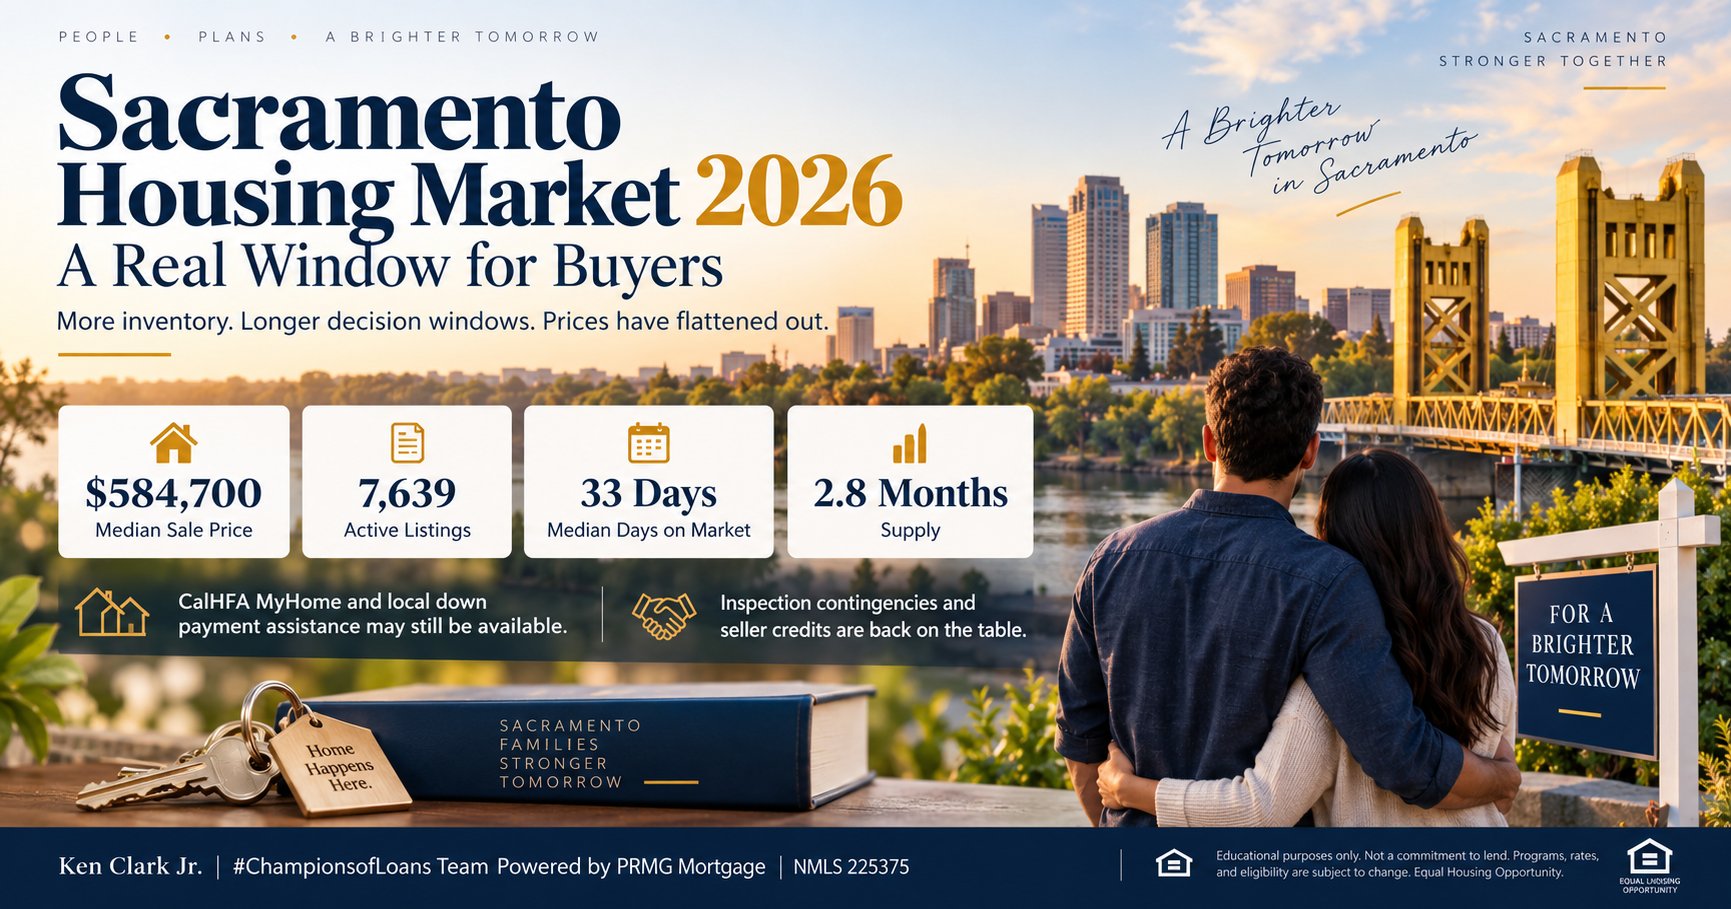
As of August 2026, Sacramento's median sale price sits right around $584,700, essentially flat, down roughly 0.8% from a year ago. There were about 7,639 active listings, and the region was running near 2.8 months of supply. Homes took a median of about 33 days to sell, and only about a third went under contract within two weeks.
Read those numbers again, because the headline version of them tends to sound negative. "Prices dip." "Homes sit longer." "Market cools."
Here is the translation for someone who actually wants to buy a house: you have choices, and you have time to think.
What "33 days on market" really buys you
When homes were selling in nine days, buyers were making six-figure decisions on a Sunday afternoon. Inspection contingencies disappeared. Appraisal contingencies disappeared. People stretched past their comfort zone because the alternative was losing the eleventh house in a row.
A 33-day market changes the negotiation itself. In this environment we are regularly seeing:
- Inspection contingencies survive. You can find out what is wrong with the roof before you own the roof.
- Seller credits come back on the table. A seller motivated by 45 days of showings may contribute toward closing costs or a rate buydown rather than cut the price outright.
- Repairs get negotiated instead of absorbed. That $9,000 HVAC replacement becomes a conversation, not a surprise.
- You can walk. Which, quietly, is the single most valuable thing a buyer can have.
None of that shows up in a median price chart. All of it shows up in your bank account.
The affordability math is doing something interesting
Two things have moved at once. Sacramento prices flattened, and mortgage rates spent the summer drifting rather than climbing. As of early September 2026, 30-year fixed rates have been hovering near the high-6% range, with 15-year products lower. The Federal Reserve meets September 15 to 16, and markets have been pricing in a possible cut, though nobody, including me, can tell you what rates will do next. Anyone who says otherwise is guessing with confidence.
What I can tell you is how to plan around uncertainty instead of betting on it.
If rates ease later, you refinance. If they do not, you already bought at a price point that was not inflated by a bidding war. The buyer who overpays by $40,000 in a frenzy carries that forever; the buyer who negotiates $10,000 in seller credits keeps it forever. Purchase price is permanent. Rates are temporary.
Sacramento is also one of the last accessible major California markets
Statewide, California's median price has been running near, and recently just below, $900,000. Sacramento's median is roughly $585,000.
That gap is the entire reason the Sacramento region keeps drawing buyers from the Bay Area, and it is also why local first-time buyers still have a legitimate shot here. And in 2026, the conforming loan limit for Sacramento County is $832,750 for a one-unit property, up $26,250 from 2025. Practically speaking, the overwhelming majority of Sacramento purchases now fall comfortably inside conventional conforming financing: no jumbo underwriting, no jumbo reserve requirements, no jumbo pricing hit.
For buyers looking in Folsom, Granite Bay, or higher-priced pockets of El Dorado County, that higher limit may be the difference between a conventional loan and a jumbo one. It is worth checking before you assume you need the harder product.
Down payment assistance: what is actually open
This is where a lot of Sacramento buyers get bad information from a headline.
California runs several programs through CalHFA, each built to work with a CalHFA first mortgage as a complete path on its own. That structure is a big part of why CalHFA can deliver competitive pricing for income-eligible buyers. For Sacramento specifically, one documented CalHFA-approved combination is available for eligible buyers: pairing a CalHFA FHA or conventional first mortgage with a SHRA CalHome or PLHA second. Availability, funding, and terms change, so use this as a starting point and confirm current guidelines with a CalHFA-approved lender when you get preapproved.
- MyHome Assistance Program. Deferred junior loan generally offering up to 3% (conventional) or 3.5% (FHA/government) of the purchase price toward down payment and closing costs. Available year-round rather than by lottery, subject to funding and eligibility.
- ZIP (Zero Interest Program). Zero-interest help toward closing costs, generally in the 2 to 3 percent range, paired with a CalHFA first mortgage.
- MyAccess. A 2.5 percent deferred-payment second loan for eligible buyers.
- Dream For All Shared Appreciation Loan. Up to 20% of purchase price, capped at $150,000, for eligible first-generation first-time buyers. Access is granted through a randomized voucher drawing rather than first-come-first-served. The 2025-26 State Budget allocated $300 million to the program, with CalHFA expecting roughly $150 million to $200 million available for 2026. The primary application window ran February 24 through March 16, 2026, with an additional voucher release noted as of May 20, 2026. If Dream For All is on your radar, the move is to get fully pre-approved and documented before the next window opens, not during it.
To keep this simple: even if Dream For All is between application windows, MyHome remains available today and continues to be a real path for many Sacramento buyers, subject to eligibility. You do not have to wait for the next Dream For All window to get moving on your purchase.
Run the math on a $585,000 Sacramento home with an FHA first mortgage. The 3.5% down payment is about $20,475. MyHome assistance at 3.5% is in the same neighborhood. For a qualified buyer, that can mean walking into a purchase with very little of their own cash toward the down payment, with closing costs and reserves still to plan for.
Eligibility is real and specific: first-time buyer status (generally no ownership interest in the past three years), county income limits, a CalHFA-approved lender, homebuyer education, and standard credit and debt-to-income underwriting. Funding availability and guidelines change. This is exactly the kind of thing to verify for your situation rather than assume from a blog post, including this one.
Beyond CalHFA: three more program paths worth asking about
CalHFA is the biggest source of California DPA, but not the only one. Depending on your county, price point, and loan type, three additional program paths may be worth reviewing to see which delivers the most benefit for your file:
- GSFA Platinum. Grants and forgivable second mortgages from a public benefit corporation, generally up to 5% of the loan amount, depending on program version and lender approval. GSFA is a separate program path from CalHFA and is generally used in place of CalHFA, not alongside it.
- SHRA (Sacramento Housing and Redevelopment Agency). Sacramento County offers CalHome and PLHA DPA for income-eligible buyers when funded. For eligible Sacramento buyers, SHRA CalHome or PLHA is the documented CalHFA-approved combination that pairs with a CalHFA FHA or conventional first mortgage, giving Sacramento buyers a stacked structure specific to this market. Subject to SHRA and lender approval and current funding cycles.
- NHF (National Homebuyers Fund). When funded, offers a forgivable loan after several years of owner occupancy. Funding is intermittent and combinability rules vary, so eligibility and current program terms should always be confirmed at the time of application.
Each program has its own eligibility and its own way of helping you buy. The right move is asking your lender to compare the ones you may qualify for so you can see the specific dollar and monthly-payment benefit each one delivers for your scenario. The DPA Finder is a quick way to see which programs may fit your file.
Reading two different pictures of the same market
If you follow Sacramento housing news, you will see two different stories playing out at the same time, and both are technically correct.
Redfin's July model puts Sacramento squarely in buyer's-market territory, estimating roughly 7,425 active sellers against about 5,603 active buyers, or 32.5% more sellers than buyers. That is a real, measurable tilt in negotiating power toward the buyer.
Meanwhile, the Sacramento Association of REALTORS describes what looks like a seller's market. June figures showed just 2.1 months of inventory, homes averaging 28 days on market, sellers receiving about 99% of original asking price, and sales up 13.4% year over year.
Is that a contradiction? No. SAR is measuring supply relative to sales. Redfin is measuring buyers relative to sellers. Put them together and you get a very unusual market: limited inventory, but even more limited buyer demand.
And here is the number that matters most for your wallet. Redfin's Sacramento concession study found that 51.9% of transactions included a seller concession in the three months ending May 2026. More than half. About 22.9% of metro listings had already taken a price cut in July. Nearly one in four sellers has blinked first.
Practically, that means the negotiation frame is different in 2026 than it was in 2022. Do not just negotiate the price. Negotiate the payment. A $10,000 seller credit toward a rate buydown often moves the monthly number more than a $10,000 price cut does. Your lender should be modeling both before you write the offer.
Why this matters beyond the monthly payment
There is a number I come back to constantly, because it reframes the entire conversation from "can I afford the payment" to "what am I building."
The Federal Reserve's Survey of Consumer Finances found that in 2022, the median net worth of a U.S. homeowner was approximately $396,200, compared to approximately $10,400 for renters and other non-homeowners.
That is not a rounding difference. It is roughly a 38-to-1 gap.
Homeownership is not the only cause. Homeowners tend to have higher incomes and save in other ways too. But a fixed-rate mortgage does something renting structurally cannot: it converts a monthly housing cost into an asset, freezes your principal-and-interest payment for three decades, and lets time do the rest. Rent has no amortization schedule.
Nobody can promise you appreciation. What a fixed mortgage can promise is that your principal and interest payment in 2036 will look exactly like it does in 2026, while Sacramento rents almost certainly will not.
Your actual next steps this month
- Get a real preapproval, not an online estimate. Full credit, income, and asset review. In a 33-day market you have time to shop, but only if you know your number.
- Ask specifically about MyHome and any city or county programs. Sacramento-area buyers sometimes qualify for local layers on top of state assistance. Ask by name.
- Compare FHA against conventional side by side. With current mortgage insurance structures and credit-based pricing, the answer is genuinely different from buyer to buyer.
- Structure your offer to use this market. Seller credits toward a rate buydown often beat an equivalent price reduction in monthly-payment terms. Your lender should be modeling both before you write.
- Do not wait for a rate forecast to be right. Buy the house you can afford at today's numbers, and treat any future rate improvement as upside rather than the plan.
Sacramento is not a distressed market. It is a normal one, and after four abnormal years, normal is the opportunity.
If you are wondering whether buying, refinancing, or using down payment assistance makes sense for your situation, connect with Ken Clark Jr. and the #ChampionsofLoans team at PRMG Mortgage. The right strategy starts with a conversation, not a guess.